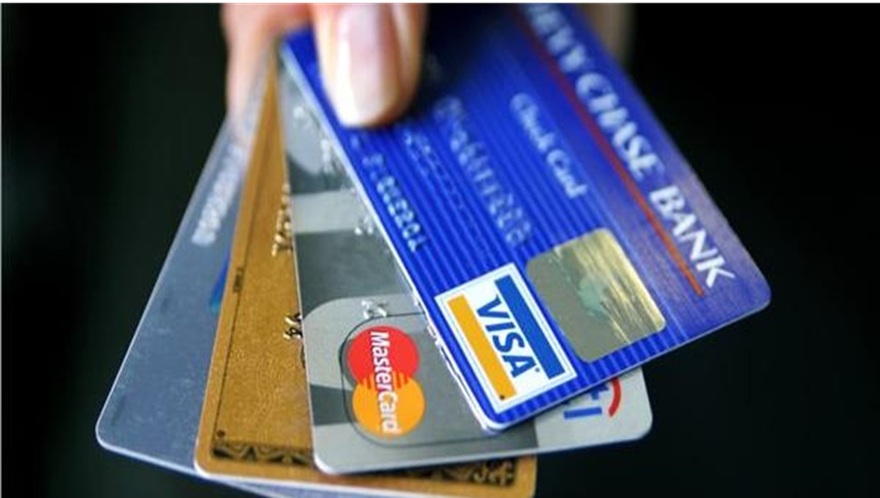
Tangem is preparing to extend its crypto payments product into physical cards, with a new Tangem Pay Visa card scheduled to launch on October 7 and offer users up to 2% cashback paid directly in USDC.
The physical card will expand Tangem Pay beyond the virtual Visa product already available inside the Tangem Wallet app. Users will be able to make purchases at Visa-accepting stores, shop online, use the card while traveling and withdraw cash from supported ATMs.
The launch is another attempt to close one of crypto’s longest-running usability gaps: converting digital assets from something users primarily hold, trade or transfer into money that can be spent through familiar payment infrastructure.
According to Tangem Pay’s current product information, the card program is issued by Rain, a Visa Principal Member, while Tangem Pay operates as a separate regulated payment product within the Tangem app. Tangem Wallet itself remains a non-custodial hardware wallet product.
Physical Cards Extend an Existing Virtual Visa Product
Tangem Pay is not starting from scratch. The company opened its virtual Visa card to eligible users in selected markets earlier in 2026, allowing customers to load stablecoins into a dedicated payment account and spend through the Visa network.
The existing product is available across selected countries in the United States, Latin America, Asia-Pacific, the Middle East and Africa, although eligibility varies by jurisdiction.
When a card transaction is made, the equivalent stablecoin amount is deducted from the Tangem Pay balance while the merchant receives conventional currency through Visa’s payment network. The model allows merchants to accept what looks like a normal card payment without needing to operate a cryptocurrency wallet or directly hold digital assets.
That structure resembles the wider push to make stablecoins usable in ordinary commerce while keeping the blockchain component largely invisible to the merchant.
The physical card scheduled for October 7 adds a more traditional form factor to that system. Tangem’s public product page still describes physical cards as coming soon, reflecting that the product has not yet formally gone live.
Cashback Is Paid in USDC Rather Than Points
Tangem is also using crypto-native rewards to make the product compete more directly with mainstream debit and credit cards.
Tangem Pay’s Basic plan currently offers 1% cashback on eligible purchases, with rewards capped at $100 per month. Plus members can earn 2%, capped at $300 per month. Cashback is deposited directly into the user’s Tangem Pay account in USDC rather than being issued as proprietary points or another reward token.
There are restrictions. Tangem says purchases must meet its eligibility requirements, while transactions below $30 do not qualify for cashback. In-store purchases at merchants in the EU and UK are also excluded from cashback because of local interchange regulations.
The company says card purchases carry no transaction fee, although foreign-exchange charges can apply when spending in currencies other than the card’s settlement currency. ATM fees also depend on the membership plan.
Cash withdrawals are currently limited to $250 per transaction, with up to three withdrawals permitted within a 24-hour period under Tangem Pay’s published terms.
Self-Custody Comes With an Important Qualification
The most interesting part of the product is not the plastic card itself. It is the attempt to connect a self-custodial crypto wallet to mainstream card infrastructure without making the user’s entire wallet balance custodial.
That distinction needs to be understood carefully.
Tangem Wallet remains separate from Tangem Pay. Users maintain control of the private keys protecting assets in their main hardware wallet, while the Visa payment service requires identity verification and operates through a dedicated payment account.
Users therefore do not simply tap a card and spend any cryptocurrency sitting anywhere inside their hardware wallet. Funds first need to be made available to Tangem Pay. Tangem says those assets remain on-chain in a user-controlled smart-contract structure, but the card layer still operates within a regulated payment program that includes identity verification and transaction monitoring.
That hybrid model is becoming increasingly common as companies try to combine the control advantages of self-custodial wallet infrastructure with the convenience and compliance requirements of conventional financial services.
Crypto Cards Are Becoming Less About Crypto
The bigger story is how little the consumer experience needs to resemble cryptocurrency.
A user can hold stablecoins, load a card account and then pay at a supermarket, hotel or online checkout through Visa. The merchant does not need to understand Polygon, USDC, private keys or blockchain settlement.
That is probably a more realistic path to mainstream crypto payments than asking millions of retailers to install dedicated wallets and accept blockchain transactions directly.
Stablecoins are increasingly moving in this direction. They are becoming financial infrastructure rather than simply trading assets, with payment firms, fintech companies and crypto platforms competing to make tokenized dollars work behind interfaces consumers already understand.
Tangem’s physical card fits neatly into that trend. The blockchain handles the asset side of the experience. Visa handles merchant acceptance. The card turns the two systems into something that looks almost indistinguishable from conventional spending.
The Real Competition Is for the Wallet Relationship
That raises a more important strategic question than whether crypto users want another card.
Who owns the financial relationship with the customer?
Historically, exchanges occupied much of that position in crypto. Users bought assets, stored balances and accessed financial products through centralized platforms. Self-custodial wallets were primarily storage and transaction tools.
Products such as Tangem Pay blur that distinction.
If a wallet can hold assets, swap tokens, generate yield, receive money and provide a Visa card for daily spending, users have fewer reasons to move funds through a centralized exchange merely to access ordinary financial services.
That does not mean exchanges disappear. They still provide liquidity, trading infrastructure, fiat access and institutional services that wallets cannot easily replicate. But wallets are moving closer to the customer-facing role historically occupied by banks and fintech apps.
There is also a security trade-off. Greater financial functionality inside self-custody products puts more responsibility on the user and makes wallet security increasingly important. Recent incidents have highlighted the difficulty of measuring losses associated with self-custody, where compromised keys or devices can create very different recovery options from fraud involving a traditional bank card.
Rewards May Attract Users, but Everyday Reliability Will Decide Adoption
The 2% USDC cashback headline gives Tangem a straightforward acquisition tool, particularly because users receive a liquid dollar-linked asset rather than points that need to be redeemed.
But rewards alone rarely determine whether a payment product becomes someone’s primary card.
The more important tests will be whether transactions are consistently approved, how smoothly refunds and disputes work, how competitive foreign-exchange and ATM costs remain, and whether users can move funds between the wallet and card account without friction.
That is where crypto payment products increasingly face the same expectations as banks.
Consumers may be interested in blockchain settlement and self-custody, but they still expect a card to work instantly at a restaurant, hotel or airport. Once crypto enters everyday payments, technical novelty matters less than reliability.
Tangem’s October 7 physical-card launch therefore represents more than another crypto accessory. It is part of a wider attempt to make the wallet itself a financial interface — one capable not only of storing digital assets, but of turning them into spendable money without forcing the user to leave the crypto ecosystem first.
Shane Neagle is a financial markets analyst and digital assets journalist specializing in cryptocurrencies, memecoins, prediction markets, and blockchain-based financial systems. His work focuses on market structure, incentive design, liquidity dynamics, and how speculative behavior emerges across decentralized platforms.
He closely covers emerging crypto narratives, including memecoin ecosystems, on-chain activity, and the role of prediction markets in pricing political, economic, and technological outcomes. His analysis examines how capital flows, trader psychology, and platform design interact to create rapid market cycles across Web3 environments.
Alongside digital assets, Shane follows broader fintech and online trading developments, particularly where traditional financial infrastructure intersects with blockchain technology. His research-driven approach emphasizes understanding why markets behave the way they do, rather than short-term price movements, helping readers navigate fast-evolving crypto and speculative markets with clearer context.